Your Pre-Approval Brought a Knife to a Cash Fight
The national headlines will tell you the housing market is resting. Buyers are patient. Prices are flat. Everyone is waiting on mortgage rates like it is a bus that might actually come.
Then there is San Francisco, which did not get the memo, and would not have opened the email anyway.
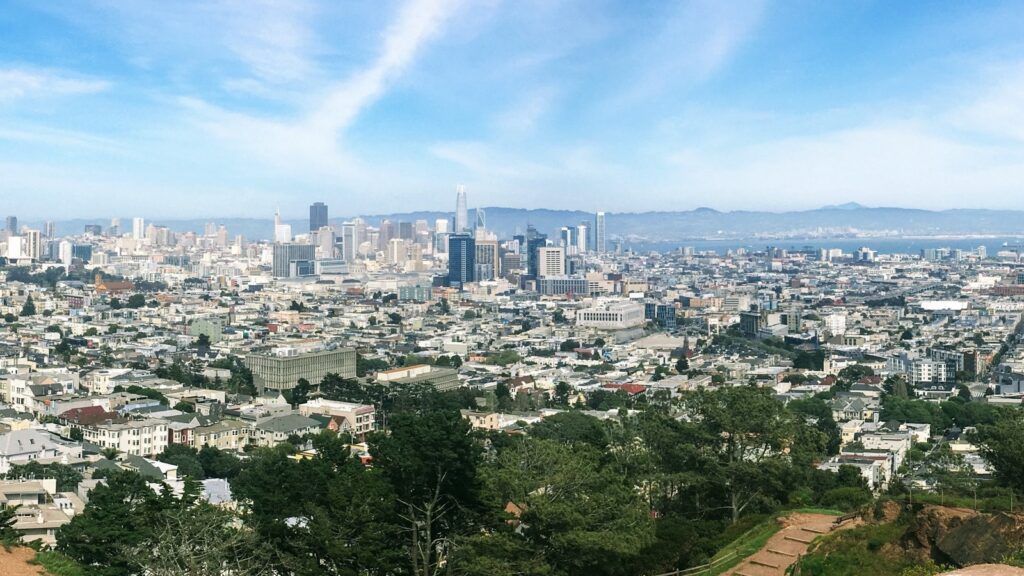
The median existing single-family home in this country sold for $440,300 in July. In San Francisco County, it was $2,050,000 — up 25.2% in a year, the largest increase of any county in California. In most of America, $440,000 buys a house with a yard and possibly a second bathroom you are allowed to be smug about. Here, it is a solid down payment on a Victorian that shares a wall, a boiler, and a complicated history with the neighbors. We are not dancing to the same song as the rest of the country, and knowing why is the difference between playing this market and getting played by it.
The money is real, and it just woke up
The popular explanation is the coming wave of tech companies going public, and I would not lean on it too hard — the economists who watch this closely say public offerings move our market less than people assume. What moves it is liquid wealth that already exists. When the market runs at records, a great many people here who are paid partly in stock can turn a number on a screen into a down payment. That is the money showing up at our open houses, wearing a vest.
The front edge of it is easy to see. In the first six months of this year, 144 San Francisco homes sold for at least a million dollars over asking. Over the same stretch last year, the number was eight. That is not a typo, and it is not Karl the Fog rolling in to blur the figures. Those homes listed for an average of $3.8 million and sold for an average of $5.3 million — the kind of math that makes a Zestimate quietly close the app and lie down.
This month gave us a clean example. A four-bedroom in Pacific Heights came on the market at $3.99 million, drew sixteen offers — the lowest of them $400,000 over asking — and sold inside of a week at $6.63 million.
Here is the part that reorders the whole game: about one in three Bay Area sales this spring were all-cash. When a third of the room does not need a loan, showing up with a mortgage pre-approval can feel like bringing a Clipper card to a Tesla dealership. Rates have eased a little — the thirty-year fixed averaged 6.65% the week of August 20, a second small weekly decline — which in this market is less a turning point and more the Fed handing out a participation trophy. Rates are not the story. Supply is. San Francisco is sitting on roughly one month of inventory against 3.4 months statewide, and sales are down 10.3% from a year ago because there is less to buy, not less appetite.
There is more than one San Francisco right now
It would be easy to write only the frenzy story. It would also be roughly half the city.
At the very top of the market, a house can draw a dozen offers and settle a million or two above where it started. This is the tier where “fixer-upper” means the wine fridge tops out at a heartbreaking 200 bottles, and “cozy” describes the second kitchen, the one the family does not cook in. In the same city, in the same week, about 18% of households can afford the median home here — a number that takes an income of roughly $535,600 to reach. Both of those things are true, sometimes on the same block. Anyone selling you a one-word verdict — “booming,” “crashing” — is describing a market they have not actually looked at.
So the headline number is almost never your number. That frenzy lives in a few pockets. Most of our buyers are not shopping at six million, and nobody should feel priced out of the conversation because someone else overpaid for a view.
If you are buying
If you are financing, you are not out of it — you just cannot beat cash on price alone. You beat it on certainty. Get fully underwritten before you write, keep your terms clean, and use every lever in an offer that has nothing to do with the number. That is the part I do with our buyers in my sleep, and it is the difference between watching a house go and getting the keys to it.
The side door is also wide open. Statewide, about 30% of households can afford the median-priced condo at $670,000, against 19% for the median single-family home at $916,750 — and condos move at a pace that will not require blood-pressure medication. For a first purchase, that gap is not a consolation prize. It is a strategy.
If you are selling
Low supply is your tailwind, but it will not carry your bags. The homes setting these records are prepped and priced to start a fight, not listed high and left in the corner to think about what they have done. That Pacific Heights house went out deliberately under the market and ended up with sixteen buyers arguing with each other. The same house, priced at what everyone hoped it was worth, sits.
The same thing holds up in Marin, where sales are running about 21% ahead of last year against a median of $1,770,000 — a genuinely active market that still punishes an optimistic number, and where a home priced wrong sits long enough that the staging lemons apply for residency. Prep and price are the entire game, and getting them right is the conversation I want to have before your home ever hits the market — not after it has been sitting there developing a reputation.
The short version
San Francisco is not defying the national market by accident. It runs on liquid money and old scarcity, not on the interest-rate soap opera everyone else is watching. It is also several markets wearing one trench coat — the city at $2,050,000, Marin at $1,770,000, the Peninsula at $2,210,000 — and figuring out which one is actually yours is where a good conversation starts.
If you are weighing a move this year, in the city or up in Marin or down the Peninsula, let’s talk through where you really fit. No pressure, no hard sell, and I will say “over asking” only the legally required number of times.
Thinking about buying or selling in San Francisco, Marin, or the Peninsula? Call or text me at (415) 407-5324, or visit Primaverarealty.com.
Beatrice Kopilenko, REALTOR® · DRE #01970797
Figures: National Association of Realtors, July 2026 existing-home sales; California Association of Realtors, July 2026 Home Sales and Price Report and Second Quarter 2026 Housing Affordability Index; Redfin, all-cash share April–June 2026; Freddie Mac Primary Mortgage Market Survey, week of August 20, 2026.